
Tesla stock gained attention after Morgan Stanley raised its bullish outlook on the company’s electric Semi truck and the potential for autonomous trucking software to become a major source of future revenue. The updated view comes as Tesla moves closer to expanding its commercial trucking business, while investors continue to watch the company’s broader push into artificial intelligence and self-driving technology.
Morgan Stanley did not raise its main Tesla price target or change its Equalweight rating. Instead, the investment bank increased the potential value it sees in Tesla’s long-term bull case, particularly if the Semi becomes part of a large autonomous trucking network.
Morgan Stanley Raises the Long-Term Bull Case
The biggest change in Morgan Stanley’s outlook is linked to autonomous trucking. The firm estimates that the U.S. autonomous trucking market could eventually reach between $500 billion and $1.1 trillion by 2041. Autonomous fleets could also reduce transportation costs by around 20% compared with traditional human-driven trucks, mainly through lower labor, fuel and insurance expenses.
For Tesla, that creates a potential opportunity that goes beyond simply selling electric trucks. If the company can successfully combine its Semi platform with autonomous-driving software, it could generate recurring revenue from trucking operators. That possibility is now becoming an important part of the long-term investment argument surrounding Tesla.
Morgan Stanley analyst Andrew Percoco estimates that autonomous software could potentially generate between $12,000 and $18,000 per month for each Tesla Semi. The estimate is based on a subscription model linked to the number of miles driven by autonomous trucks.
Tesla Semi Could Become More Than an Electric Truck
Tesla’s Semi was initially viewed mainly as an effort to bring electric powertrains into the heavy-duty transportation market. However, the company’s growing focus on software and autonomy could give the vehicle a much larger role.
Morgan Stanley estimates that Tesla could have about 82,000 Semis operating by 2040. Under its bullish scenario, those trucks could produce approximately $17 billion in software revenue and $7.5 billion in earnings before interest and taxes.
That projection explains why investors are paying greater attention to the Semi. The vehicle itself could generate revenue through sales, but autonomous software could potentially provide a recurring income stream after trucks are already on the road.
This model would be particularly important for Tesla because software revenue can carry different economics from traditional vehicle sales. Instead of relying entirely on selling new vehicles every year, Tesla could potentially earn ongoing payments from existing commercial fleets.
Rising Diesel Prices Add to the Appeal
Another factor supporting interest in the Tesla Semi is the sharp increase in diesel prices. U.S. diesel prices recently reached about $6 per gallon, increasing operating costs for trucking companies. Higher fuel costs can make electric trucks more attractive to fleet operators, particularly those that travel long distances and consume large amounts of diesel.
The economics of switching from diesel to electric depend on several factors, including vehicle prices, charging infrastructure, electricity costs, government incentives and the distance a truck travels. Tesla therefore still faces challenges in convincing large fleets that the Semi can deliver attractive savings over its full operating life.
However, expensive diesel creates an additional incentive for companies to consider alternatives. If Tesla can demonstrate reliable performance and lower operating costs, the Semi could become more competitive in a market where fuel expenses are a major part of fleet budgets.
Tesla Stock Still Faces Important Risks
Despite the optimistic bull case, investors should not assume that Morgan Stanley’s projection represents a guaranteed outcome. The bank has maintained an Equalweight rating and a $400 price target for Tesla, showing that its near-term view remains more cautious.
One major uncertainty is autonomous driving. Tesla has ambitious plans for self-driving technology, but achieving reliable commercial-scale autonomy is considerably more difficult than developing driver-assistance features.
Regulatory approval is another challenge. Autonomous trucks would need to satisfy safety requirements across different jurisdictions before operating widely without human drivers. Companies may also require years of testing before fully autonomous freight operations become common.
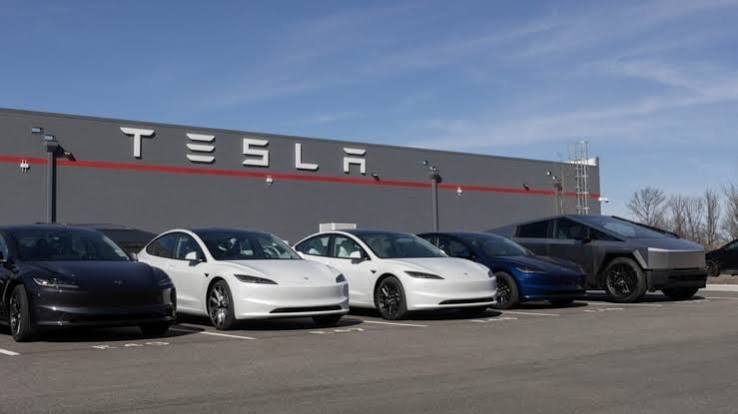
Tesla must also prove that it can manufacture the Semi at scale while maintaining quality and controlling costs. The company has been moving toward higher-volume Semi production, but commercial trucking requires different manufacturing, service and charging considerations than passenger vehicles.
Why Investors Are Watching the Semi
The renewed attention on the Tesla Semi reflects a broader change in how investors view Tesla. The company is no longer being valued only as an electric vehicle manufacturer. Its potential businesses include autonomous transportation, software, artificial intelligence and energy products.
That creates both opportunity and uncertainty. If Tesla successfully develops autonomous trucking and builds a large commercial fleet, the Semi could become an important platform for recurring software revenue. Morgan Stanley’s latest bull-case adjustment suggests that the market opportunity could be much larger than the value of truck sales alone.
At the same time, much of that potential remains dependent on future technological and commercial developments. Investors will likely look for evidence that Tesla can deliver reliable autonomous systems, expand Semi production and attract major fleet customers.
The Bigger Picture for Tesla Stock
Tesla stock continues to attract strong interest because investors are trying to determine how much of the company’s future growth could come from businesses outside traditional electric vehicle sales.
Morgan Stanley’s latest analysis gives the Semi a larger role in that discussion. Its projected autonomous trucking opportunity highlights the possibility that Tesla could eventually earn substantial recurring software revenue from commercial vehicles.
For now, however, the Semi remains a developing part of Tesla’s broader strategy. The company still needs to prove that autonomous trucking can move from an ambitious concept to a commercially viable business. If it succeeds, the Semi could become one of Tesla’s most important long-term growth opportunities. If progress is slower than expected, investors may continue to question the high expectations already built into the stock.
The latest Morgan Stanley view therefore offers a more bullish long-term scenario rather than a guarantee. For investors, the key question is whether Tesla can turn its technology ambitions into profitable, large-scale commercial operations.
